Starting January 1, 2026, the VAT rate for accommodation (short-term stays in glamping accommodations, hotels, guesthouses, holiday homes, and B&Bs) will change from 9% to 21%. Camping—renting a pitch where guests pitch their own tent, caravan, or campervan—will continue to be subject to the 9% rate.
In this article, we (Editor's note: CampPlus) explain the changes, provide practical examples, and answer the frequently asked question: will a camping pitch with private sanitary facilities remain below 9%?
What will change as of January 1, 2026?
- The reduced 9% VAT rate for accommodation will be abolished. Accommodation services will fall under the general rate of 21% from 2026.
- This applies to, among others: hotel rooms, holiday homes, B&Bs, guesthouses, hostels, short-stay apartments, furnished mobile homes and furnished (glamping) tents.
- Important for reservations and vouchers: if payment is made (partially) in 2025 for a stay in 2026 or later, 21% will apply to that payment/voucher.
Official sources:
- Tax Authorities – VAT rate accommodation (including changes from 2026 and rules for reservations/vouchers)
- Central government – Explanatory Memorandum Tax Plan 2025 (abolition of reduced VAT on accommodation)
- Entrepreneurs Square (RVO) – VAT on hotel stays increased
- HISWA-RECRON – News about VAT increase for recreational companies from 2026
What remains is 9%?
- Camping: offering camping facilities for a short period (guests bring their own tent, caravan, trailer tent or camper) remains subject to the 9% rate.
- Additional services related to providing camping facilities also remain at 9%, such as:
- supply of gas, electricity, water;
- sanitary facilities, washing and shower facilities;
- facilities for washing/drying clothes;
- parking in combination with the camping site.
Official source: Tax and Customs Administration – VAT rate for providing camping facilities (with a list of 'services associated with camping')
Camping pitch with private sanitary facilities – what is the rate?
Short answer: in most cases, 9% still applies.
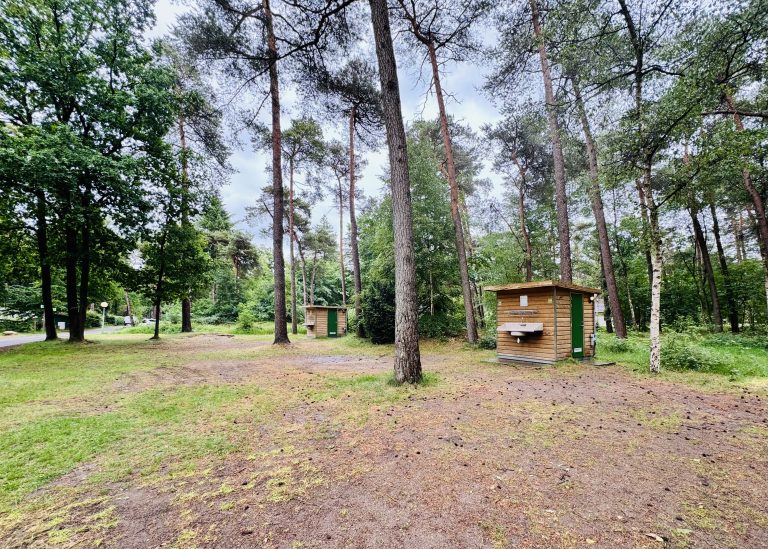
Why? The Dutch Tax and Customs Administration explicitly lists sanitary facilities as a service inherent in providing camping facilities. As long as the service is essentially renting out a plot of land where guests can set up their own camping equipment, it's considered camping. The fact that you offer private sanitary facilities (a private shower/toilet unit at the pitch or exclusive access to a lockable sanitary cubicle) doesn't change the essence: it remains a camping pitch with associated facilities.
When will it be 21%?
The 21% rate may apply if the product is no longer actually a camping pitch, but a (furnished) accommodation. Consider:
- rental of furnished glamping tents that are ready (guests do not bring anything);
- rental of chalets/mobile homes that you operate as an entrepreneur;
- packages where the pitch is an integral part of a fully furnished accommodation unit.
Tip: Determine your primary provision. Is that a pitch and infrastructure (including private sanitary facilities)? → 9%. Is that a ready-made accommodation unit? → 21%.
Practical examples
- Comfort pitch with private sanitary facilities (guest brings own caravan) → 9% (camping facilities + sanitary facilities that come with camping)
- Safari tent with private bathroom, placed and furnished by the campsite → 21% (furnished accommodation)
- Pitch + private sanitary unit (lockable, exclusive use) → 9%, provided that the core service remains camping and the unit is provided as a facility with the pitch.
- Pitch + subletting of the guest's own mobile home to third parties → The campsite owner invoices 9% for the pitch; the guest (as a business owner) usually invoices the final guest 21% for the accommodation. (Depending on the situation/KOR/business owner – ask your advisor.)
Frequently Asked Questions (FAQ)
Does a "super comfort pitch" with private sanitary facilities fall under 9%? Yes, as long as the guest brings their own camping equipment and the sanitary facilities are part of the pitch.
And what about private sanitary facilities that can only be booked via a separate key surcharge? In that case too, it is in principle a facility included in the camping service → 9%. Do clearly state it as a surcharge for a pitch on your invoice.
When is it 'no longer camping'? As soon as you provide a furnished, self-maintained accommodation unit (tent/chalet/mobile home), it qualifies as lodging → 21% in 2026.
Want to know more or need help updating your details? Would you like to know how to smartly adjust your rates, VAT codes, or guest communication before 2026? Feel free to contact us via www.campplus.nl or send an email to info@campplus.nl.
Disclaimer
This article is intended as a practical guide and does not constitute (individual) tax advice. Discuss borderline cases (e.g., glamping concepts or package deals) with your tax advisor or the Business Tax Helpline.